Cash in bank accounts
Used for pay out dollars on exchange right away
- Pro: already money, nothing to sell
- Con: can get stuck if a bank fails
- Con: transfers move only during bank hours
Picture a pawnshop. You hand over an item and get a pawn ticket. The ticket itself is worth nothing; its value lies in the fact that you get your item back with it. If the item is no longer in the pawnshop, or the pawnshop has closed, the ticket loses its value. A stablecoin token is valuable in the same way, because of the reserve behind it.
With a fiat stablecoin, meaning one backed by ordinary money, the issuer creates new tokens when it receives dollars and destroys tokens when it pays dollars back in an exchange. So it must hold at least as much in reserves as there are tokens in circulation, that is, issued and not yet handed back1. How tokens come into being and disappear in general is explained in what is issuance.
From here on, the article covers only stablecoins with a company behind them. The article what is a stablecoin explains how the other kinds differ from them.
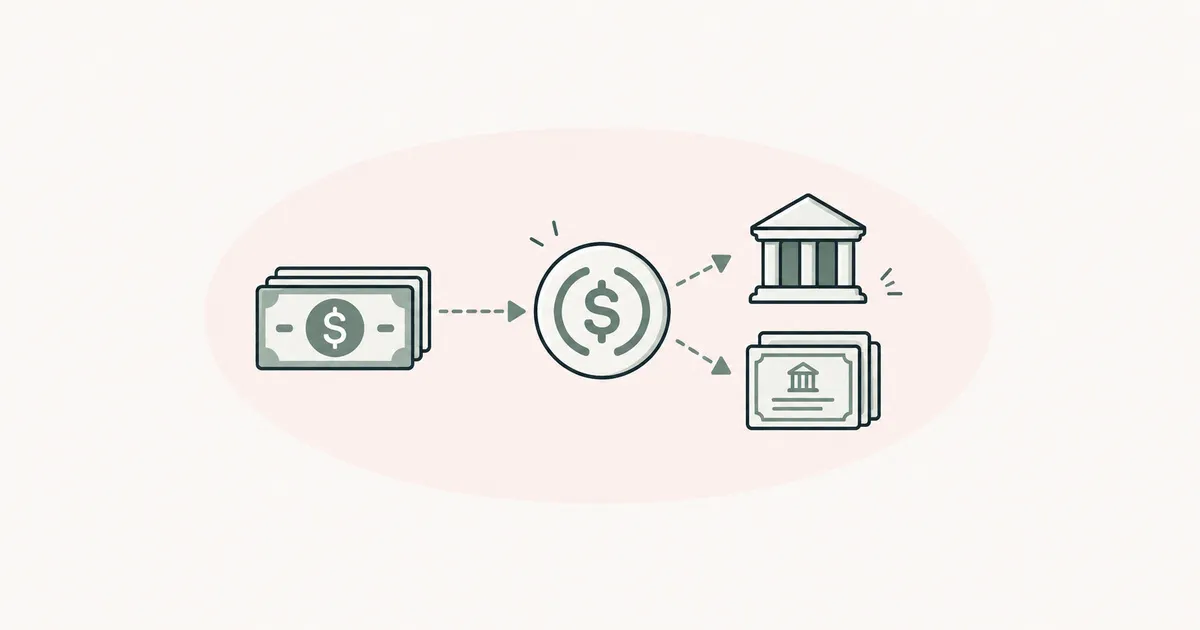
Most of the money behind USDC sits in a special fund that holds only cash and short-term US Treasury bonds. The rest of the USDC reserves is cash in accounts at a few large banks1.
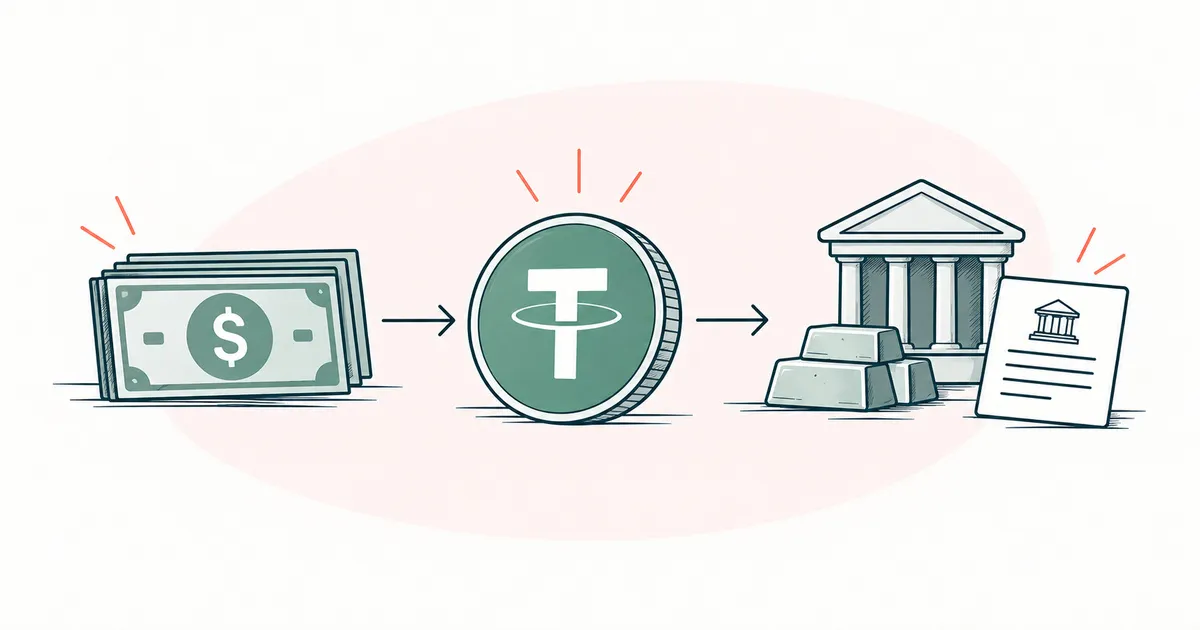
USDT reserves are mostly short-term US Treasury bonds and cash, and on 30.10.2026 they also included other assets, such as bitcoin and gold2. The shares change every month, so look them up with the issuers themselves.
Reserve liquidity is how quickly, and without losses, reserves can be turned into dollars when many people want to exchange their tokens at once. Money on your card you can spend the same minute, a term deposit you can withdraw within a day, while an apartment usually cannot be sold at full price within a week. Cash and short-term Treasury bonds are closer to money on a card; bitcoin, gold and loans are closer to the apartment.
The list of reserves allowed by the US stablecoin law (GENIUS Act) contains only cash and short-term government debt, with no bitcoin and no gold ⚖️3. The law was passed in July 2025 and is due to take effect on 18 January 2027 ⚖️4.
The part of the reserves held at that bank may become unavailable for a while, and the issuer risks not getting all of that money back. Deposit insurance protects the bank's depositor, which in this case is the issuer, and only up to a limit. In the US the limit is $250,000 per depositor at one bank ⚖️5, so for reserves worth billions of dollars this limit covers only a tiny share.
As long as the money cannot be reached, it is harder for the issuer to pay dollars to those handing tokens back, and the token's price on exchanges can drop below one dollar. In March 2023 part of the USDC reserves got stuck this way at Silicon Valley Bank; the details of that case are collected in the article on depegs. For a holder this means that the larger the share of reserves held in Treasury bonds and spread across several banks, the less a single bank's failure matters.
The first source of information is the issuer itself. Circle discloses the composition of USDC reserves every week1, and Tether usually publishes every day how much USDT is in circulation6. These are a company's figures about itself, which is why an independent auditing firm confirms them.
That confirmation comes in two kinds. An attestation is like counting the cash register at the end of the day, and an audit is like checking a shop's entire books for the year.
| Attestation | Audit | |
|---|---|---|
| What is checked | reserves and tokens issued | all company accounts |
| Period covered | one date | one year |
| Company debts | usually not | checked |
USDC reserves are checked every month by a large auditing firm1, and USDT reserves once a quarter2. In August 2026 Tether announced that it had passed a full audit of its 2025 accounts for the first time, but as of 30.10.2026 the company had not published the accounts themselves78.
A snapshot taken on one date is easy to overrate. Such a report is not an audit: it describes assets at a single moment, and assets can be borrowed for the date that matters9.
Independent checks also matter because an issuer's words about its reserves have already turned out to differ from reality. In 2021 the US commodity markets regulator (CFTC) found that in 2016 to 2018 Tether often had less money than tokens, and fined the company ⚖️10. The Tether profile goes through this story in detail.
Before you keep savings in a stablecoin, open the issuer's transparency page, where it publishes its reports, and look at:
If there is no recent report, or the report does not name the firm that checked it, hold off on keeping a large sum in that stablecoin.
Directly with the issuer, tokens are exchanged above all by its verified customers, mostly businesses, while everyone else buys and sells tokens on exchanges11. At Circle, such customers work through the Circle Mint service12. The exception is the European Economic Area (EEA). There any holder can exchange USDC and EURC with Circle after an identity check, provided they have an account at a bank in the EEA ⚖️13.
Tether exchanges USDT directly for verified customers, from a large amount upward and for a fee14.
If direct exchange is not open to you, you sell the stablecoin on an exchange or to other people at the market price, and the guide to selling and cashing out shows how to do it. Why the market price usually stays near one dollar, and when it slides down, is covered in what is a depeg.
The fund holding the bulk of USDC reserves is called the Circle Reserve Fund. It is a money market fund registered with the US Securities and Exchange Commission (SEC), it is managed by BlackRock, and BlackRock publishes the fund's data daily. Besides cash and Treasury bonds, the fund holds overnight repo deals, that is, one-day loans secured by Treasury bonds1.
The USDC attestation is carried out by a "Big Four" firm under the standards of the American Institute of Certified Public Accountants (AICPA)1. The USDT reserve report is prepared by the auditing firm BDO2, and the full audit of Tether for 2025 was done by KPMG7.
According to the CFTC's findings, Tether held enough dollars for all USDT in circulation on only 27.6% of the days in the period reviewed. The company did not disclose that it counted unsecured debts owed to Tether by other companies, along with other assets, as reserves, and it was fined 41 million dollars ⚖️10.
The GENIUS Act list includes US dollar cash, demand deposits at banks, and US Treasury bonds with no more than 93 days left until maturity. It also covers overnight repo deals backed by such bonds and shares in government money market funds ⚖️3. From 18 January 2027 the law requires US issuers to publish the composition of their reserves on their website every month, and a registered auditing firm to examine that report every month ⚖️3. Under the same law, issuers must publish their redemption rules together with all fees ⚖️3.
In the EEA, Circle redeems USDC and EURC without a fee of its own and within up to 5 business days ⚖️13.