Backed by money
Used for digital dollars or euros from a company
- Pro: the issuer promises a reserve per token
- Pro: the company promises one-to-one exchange
- Con: only as reliable as the company
- Con: direct redemption usually not open to all
The price of most cryptocurrencies changes a lot: one price today, another tomorrow. The stablecoin was invented so that the price stays put. That is where the name comes from, a "stable" coin.
The simplest way to think of a stablecoin is as a familiar dollar or euro, only recorded on a blockchain, the shared record of transfers kept at the same time by thousands of computers. You keep it in a crypto wallet and can send it to someone in another country within minutes, at night and on non-working days too.
Technically, a stablecoin is a token, that is, crypto issued on top of someone else's network, such as Ethereum or Tron. The fee for a transfer is usually paid in that network's coin, its own cryptocurrency such as ETH or TRX. How tokens work is explained in what is a token.
Stablecoins come in three kinds, depending on what backs the token1. The kind decides whom you are trusting when you hold the token.
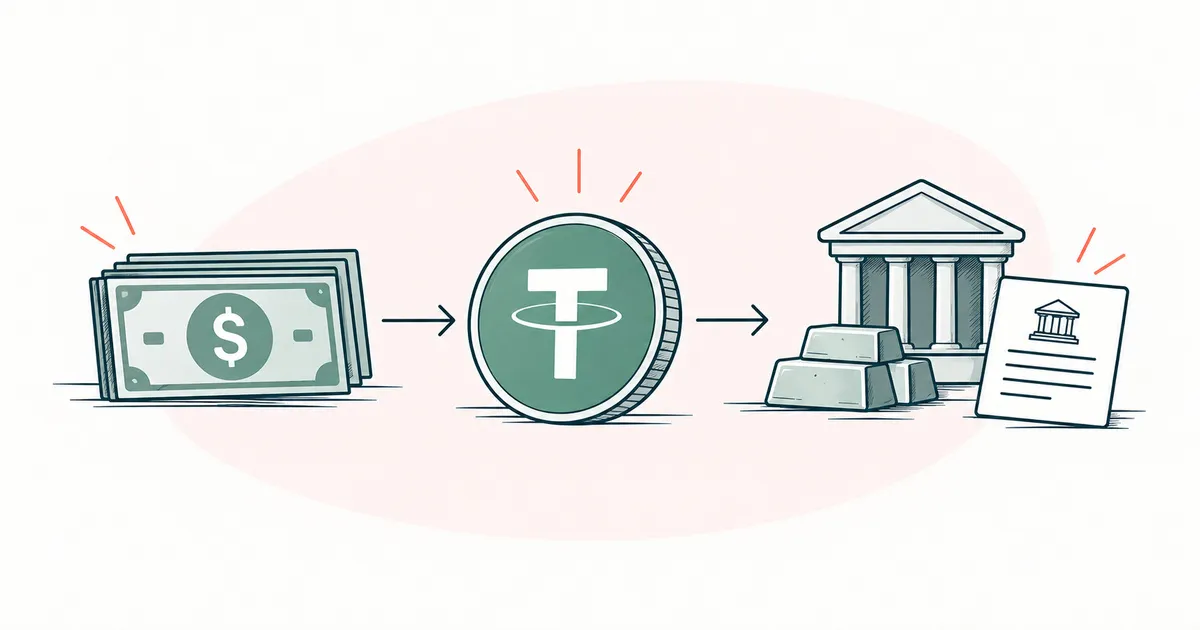
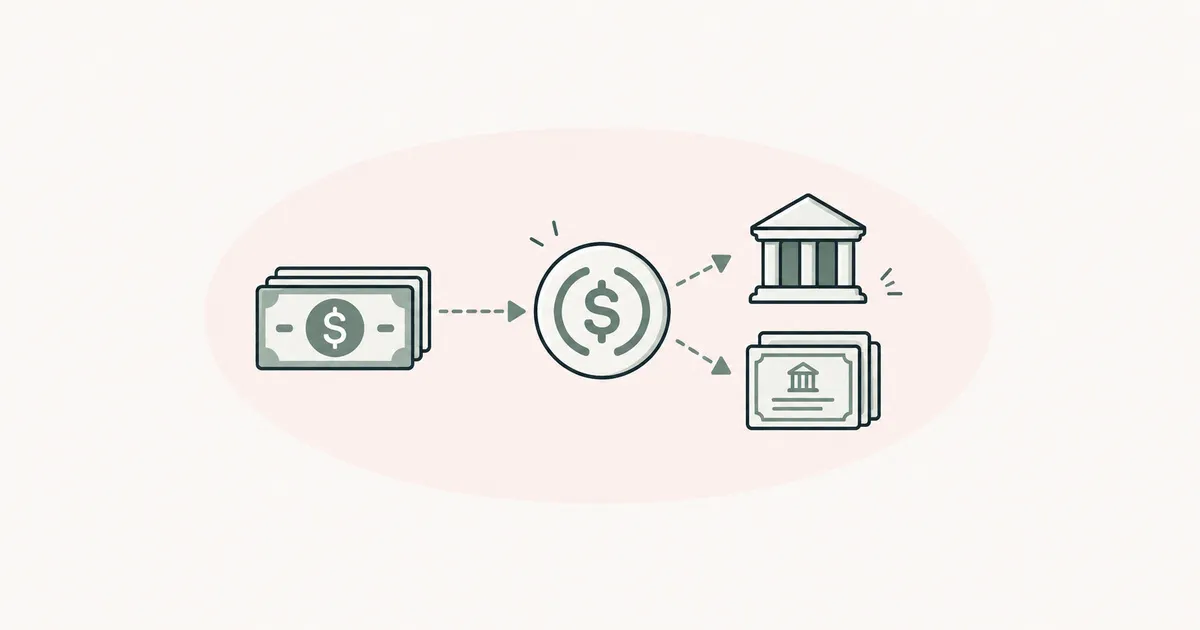
Such stablecoins are also called fiat-backed. New tokens are issued by the issuing company when it receives money, and when they are exchanged back, the tokens are burned, that is, destroyed. The reserves consist of money in bank accounts and assets that are easy to turn into money, such as government bonds (a government's IOUs)1. What counts as a good reserve and how it is checked is covered in what are reserves.
An ordinary holder exchanges a stablecoin for money on an exchange or with other people. Directly with the issuing company, tokens are exchanged by its verified customers, most of them businesses. Tether buys back USDT one to one minus a fee, and only from a large amount upward2
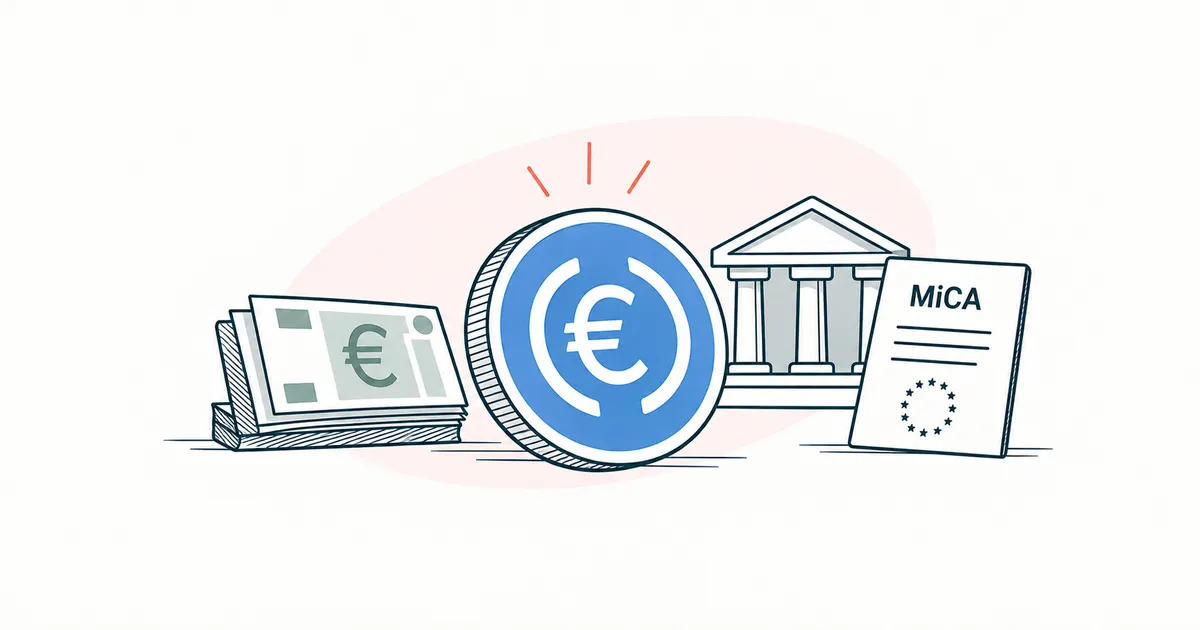
, and Circle redeems USDC for direct customers who have passed its vetting1. The exception is the countries of the European Economic Area (EEA). There, under the European rules (MiCA), any holder can redeem USDC and EURC with Circle after an identity check, provided they have an account at a bank in one of those countries ⚖️3.
On an exchange, the price is set by the buyers and sellers on that platform, so it wobbles slightly around one dollar. The issuer's direct customers pull it back to the dollar, because they can exchange the token with the company for exactly one dollar1. If someone were selling a dollar for 95 cents, buyers would snap it all up fast and the discount would vanish. Small price swings are normal, and a noticeable move away from the dollar is called a depeg, and the article on depegs explains it.
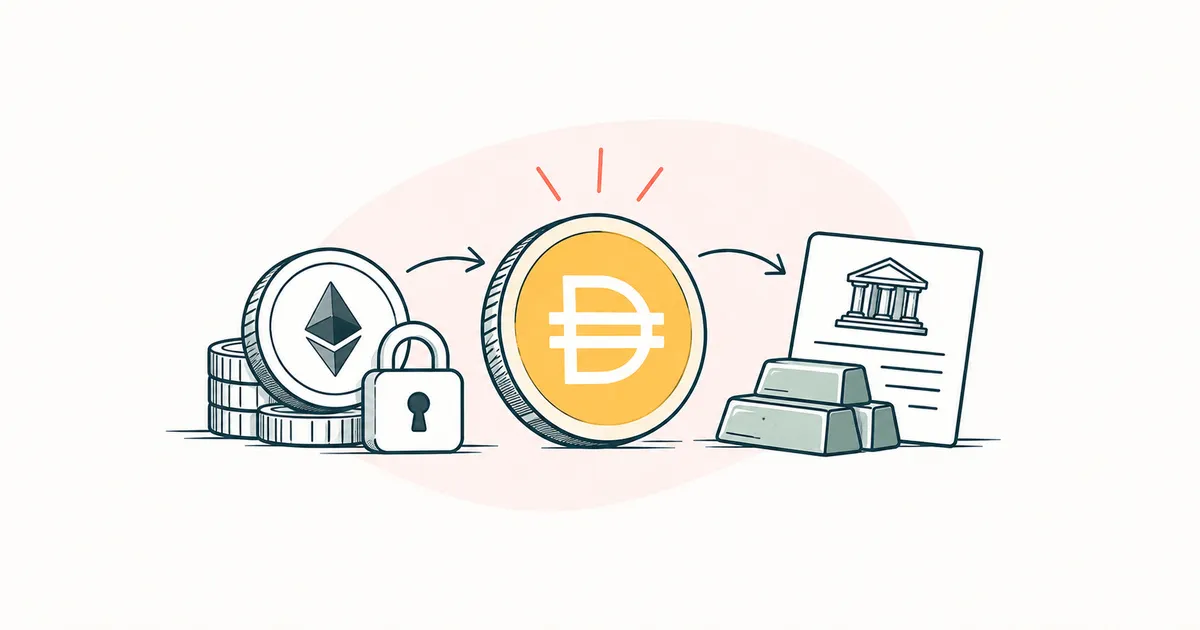
Behind such stablecoins stands another cryptocurrency, held by a program on the blockchain, that is, a smart contract. Any user of the Ethereum network can get DAI by depositing crypto into this program as collateral1. The collateral is worth more than the DAI issued against it: in 2022, DAI was backed by ether (ETH) with a 150% cushion4. This cushion is called over-collateralization, and it is there in case the collateral loses value. What the collateral consists of today, and what happens when it gets cheaper, is covered in the DAI profile.
An algorithmic stablecoin has no full backing, and its price is held by an exchange rule written into the program. The UST token on the Terra network worked this way. The program promised that for one UST it would always hand out one dollar's worth of LUNA, the Terra network's own cryptocurrency, however many coins that took, and the other way round4.
While people valued LUNA, this exchange kept UST near one dollar. Once holders began handing in UST en masse for LUNA, the program had to issue more and more new LUNA, and the coin kept falling in price. In May 2022 UST lost its peg, and it was later taken off the major exchanges4. In the view of an economist at the Federal Reserve Bank of Richmond, stablecoins backed by money or by cryptocurrency are more stable than algorithmic ones4.
Most often a stablecoin is pegged to the US dollar5. The current breakdown by currency is shown by aggregators, sites that collect summary statistics.
Circle exchanges the euro-pegged EURC for euros one to one for its customers, and in the EEA for any holder ⚖️63. That is why it usually trades at about one euro, while its price in dollars moves with the euro exchange rate.
Some tokens are pegged to gold. Each PAXG token from the company Paxos is backed by an ounce of gold held in storage7, and its price follows the price of gold.
If you live in one currency but hold a stablecoin pegged to another, its value in your currency changes along with the exchange rate between the two.
By the end of 2025 the amount of stablecoins issued had doubled in two years, and the growth is mainly tied to crypto trading8. On exchanges, people pay with stablecoins when they buy other cryptocurrency.
In countries with high inflation, people keep their savings in dollar stablecoins. In Argentina, stablecoins made up more than half of crypto transaction volume in 2024, which is linked to protecting money from inflation and from the falling value of the local currency9. How to keep savings in a stablecoin step by step, and what to watch for, is covered in protecting savings from inflation.
Stablecoins are also used to send money to relatives in another country and to get paid by clients abroad, and such transfers are growing across Latin America9. The whole route is described step by step in sending money to family and freelance payments.
Yes, a steady price does not make a stablecoin risk-free. You can lose money in several ways:
That depends on whether the reserves are enough and whether the law protects holders from the company's other creditors. While the case is being settled, the token's price on exchanges can fall below one dollar. Circle, for example, states that USDC reserves are held for the benefit of USDC holders13. How US law handles this is described in the last section, and where reserves are kept and what that means for a holder is explained in what are reserves.
In the United States, the stablecoin law known as the GENIUS Act puts holders first in line for the reserves in an issuer bankruptcy, and the law is due to take effect on 18 January 2027 ⚖️1415. Lawyers still argue over how quickly and how fully this protection would work in practice16.
DAI is run by the Sky protocol, formerly MakerDAO. In 2024 DAI got a successor, USDS, and DAI can be swapped for it one to one17.